At about half past one in the morning, on an ordinary night, Dubai International is at its busiest. That is when the long haul waves meet: the aircraft that left Europe in the evening arriving, the aircraft for Asia and Australia departing, and forty thousand people in a terminal moving between them. The airport was built around that hour and the airline that owns most of it exists because of it.
Figures reported last week put passenger traffic through the airport in March down 66 percent year on year.
What follows is an accounting of that number: what it consists of, who carries the loss, and what it costs beyond the airport itself.
Why the fall is so much steeper than the war
A two thirds fall is far larger than the reduction in people wanting to travel, and the gap is explained by what kind of airport this is.
Dubai is a connecting hub. A very large share of its passengers are not going to Dubai and never leave the terminal; they arrive from one place and depart for another, and the airport’s business is selling the connection rather than the destination.
A connection is uniquely fragile. A passenger flying from Manchester to Bangkok has several hubs to choose from, and the choice is made on price and schedule and, at the moment, on whether the route passes through airspace anybody is worried about. Switching costs nothing. The passenger simply buys a different ticket.
So the traffic did not mostly stop traveling. It went through Istanbul, or Doha where it could, or over the pole, or on a one stop routing that avoids the region altogether. The airport lost a share of a market rather than a share of demand, and that is a much worse thing to lose because the passenger has now discovered that the alternative works.
What it costs, and to whom
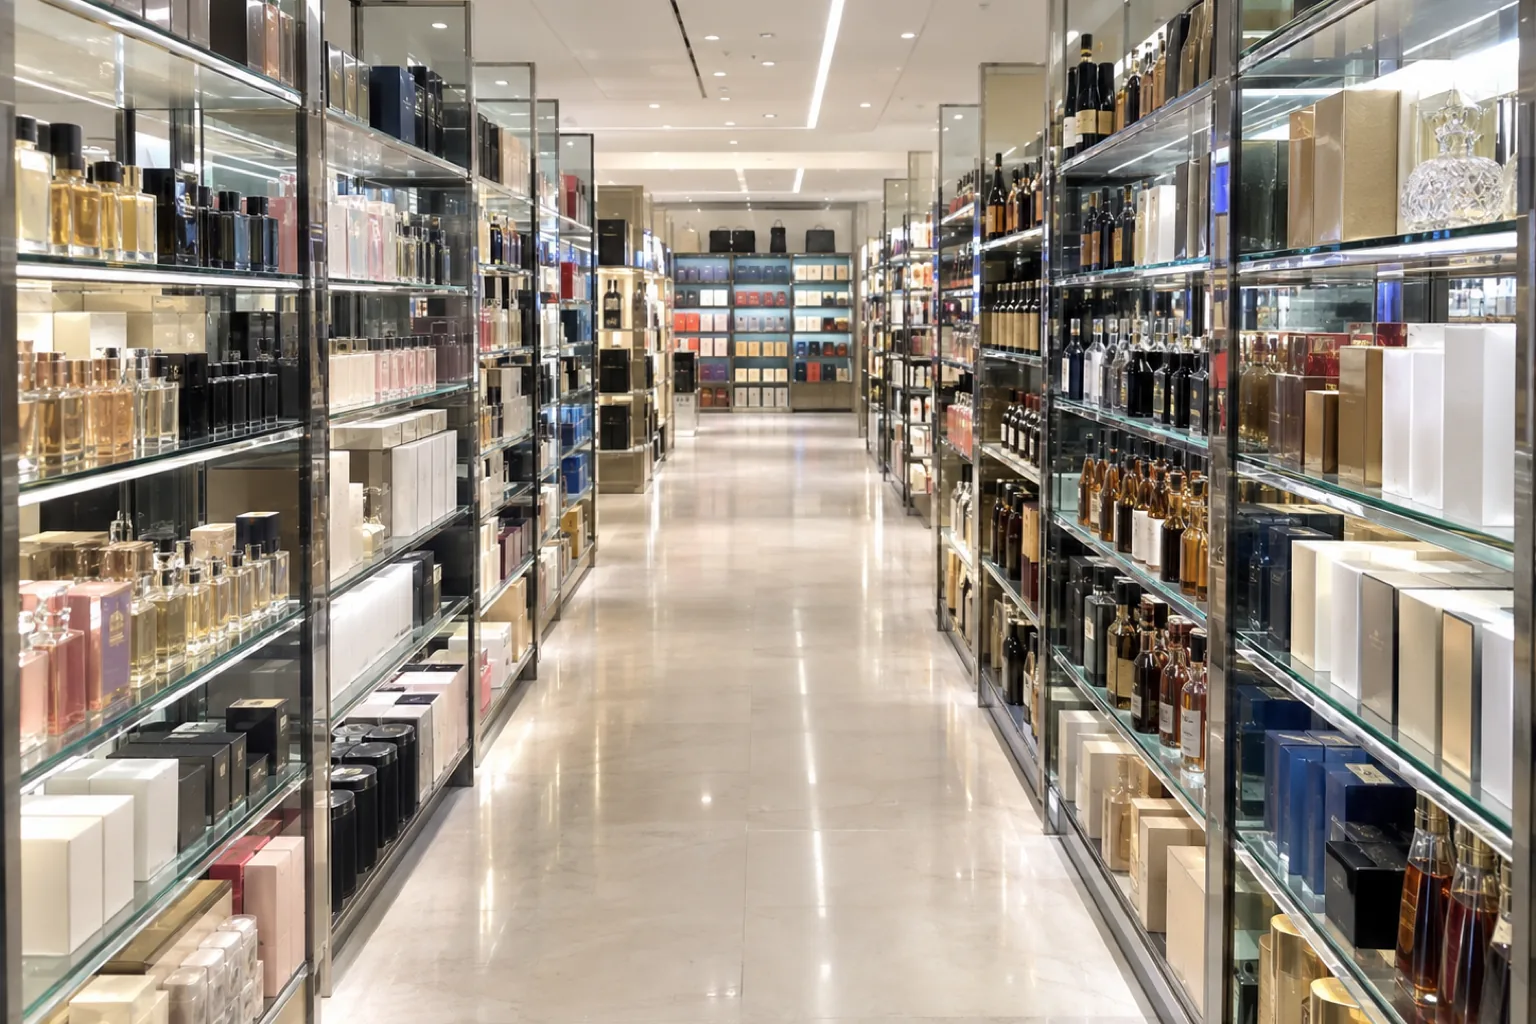
The airport. Aeronautical revenue falls with the movements: landing fees, parking, passenger charges. But the larger loss is retail, and a hub terminal is a shopping center with aircraft attached. Duty free, food, lounges and parking are high margin and they are a direct function of how many people are standing in the building at half past one in the morning.
The home carrier. A hub airline cannot shrink proportionally. Its network is a bank of connections, and the value of each flight depends on the others being there to connect to. Canceling a third of the departures does not remove a third of the cost; it removes a disproportionate share of the connecting itineraries that made the rest viable. This is why hub carriers keep flying loss making sectors during a shock, and why they lose so much doing it.
The staff and the city. An airport of this size is among the largest employers in its economy, and the employment is heavily weighted toward people on wages that do not absorb a reduction in hours. Beyond that sit the hotels, the ground transport and the retail concessions, all of which sized themselves to a level of traffic that stopped in March.
Who collects
The hubs outside the affected airspace, and the arithmetic is close to zero sum in the short run. Traffic that has to route around a region goes through whichever hub is convenient, and for European and Asian connections there are several.
Whether that advantage persists is the interesting question and it is not obvious. A passenger who has now flown a different routing twice and found it acceptable has updated their default, and defaults are sticky. Some portion of this traffic does not come back when the airspace reopens, and nobody will be able to measure which portion.
What the number does not capture
Two things, and both make the position worse than 66 percent suggests.
The first is mix. The traffic that stops first in a security event is discretionary leisure travel, which is price sensitive and books late. The traffic that continues is business and essential travel, which is less price sensitive but is also a much smaller number of people spending very little time in the terminal. So the retail loss is steeper than the passenger loss, and the passenger loss is already two thirds.
The second is cargo, which nobody counts in a passenger figure and which moves substantially in the holds of passenger aircraft. Fewer wide body movements means less belly capacity, on a set of routes that carry a great deal of high value freight, and the rates on what remains have gone accordingly.
The instrument nobody outside the industry sees
There is a mechanism underneath a hub’s economics that explains why the losses are worse than the traffic figure, and it is the slot.
A slot is a right to operate a movement at a specific time at a congested airport, and at a hub it is the most valuable thing an airline holds. Slots at the peak connecting hours are effectively impossible to buy and are allocated on the basis of historic use, with a rule requiring an operator to use a certain proportion of them or lose them.
In normal conditions that rule disciplines hoarding. In a collapse it produces a perverse result: an airline with no passengers still has a reason to fly, because not flying risks the slot, and the slot is worth more than the loss on the sector.
Regulators generally suspend the requirement during a crisis, and did so extensively in 2020. Whether it has been suspended here, and for how long, determines whether the carriers are currently flying empty airplanes to protect an asset. That is a decision taken by coordinators and transport ministries, reported almost nowhere, and worth more to an airline’s quarter than most of what is reported.
What recovery actually requires
Not the end of the war. The end of the war plus a period during which nothing happens.
Airlines schedule seasons ahead and sell tickets months ahead, so a route restored in August is a route generating revenue in the winter. Insurance and overflight decisions lag the political situation. And passengers booking a holiday six months out are making a judgment about a region rather than about a week.
Which means the recovery curve for a hub like this is measured from the point at which the situation became boring, not from the point at which it stopped being dangerous, and those are separated by a period nobody can forecast.
Half past one
The hour is still there in the schedule, because a schedule is filed in advance and the slots are held whether or not they are worth operating.
What is different is the building. The moving walkways run, the departure boards cycle, the cleaning crews work through a terminal that was designed to be uncomfortable when full and is now the other thing, which is a very large lit room at night with a few hundred people in it and a great deal of polished floor.