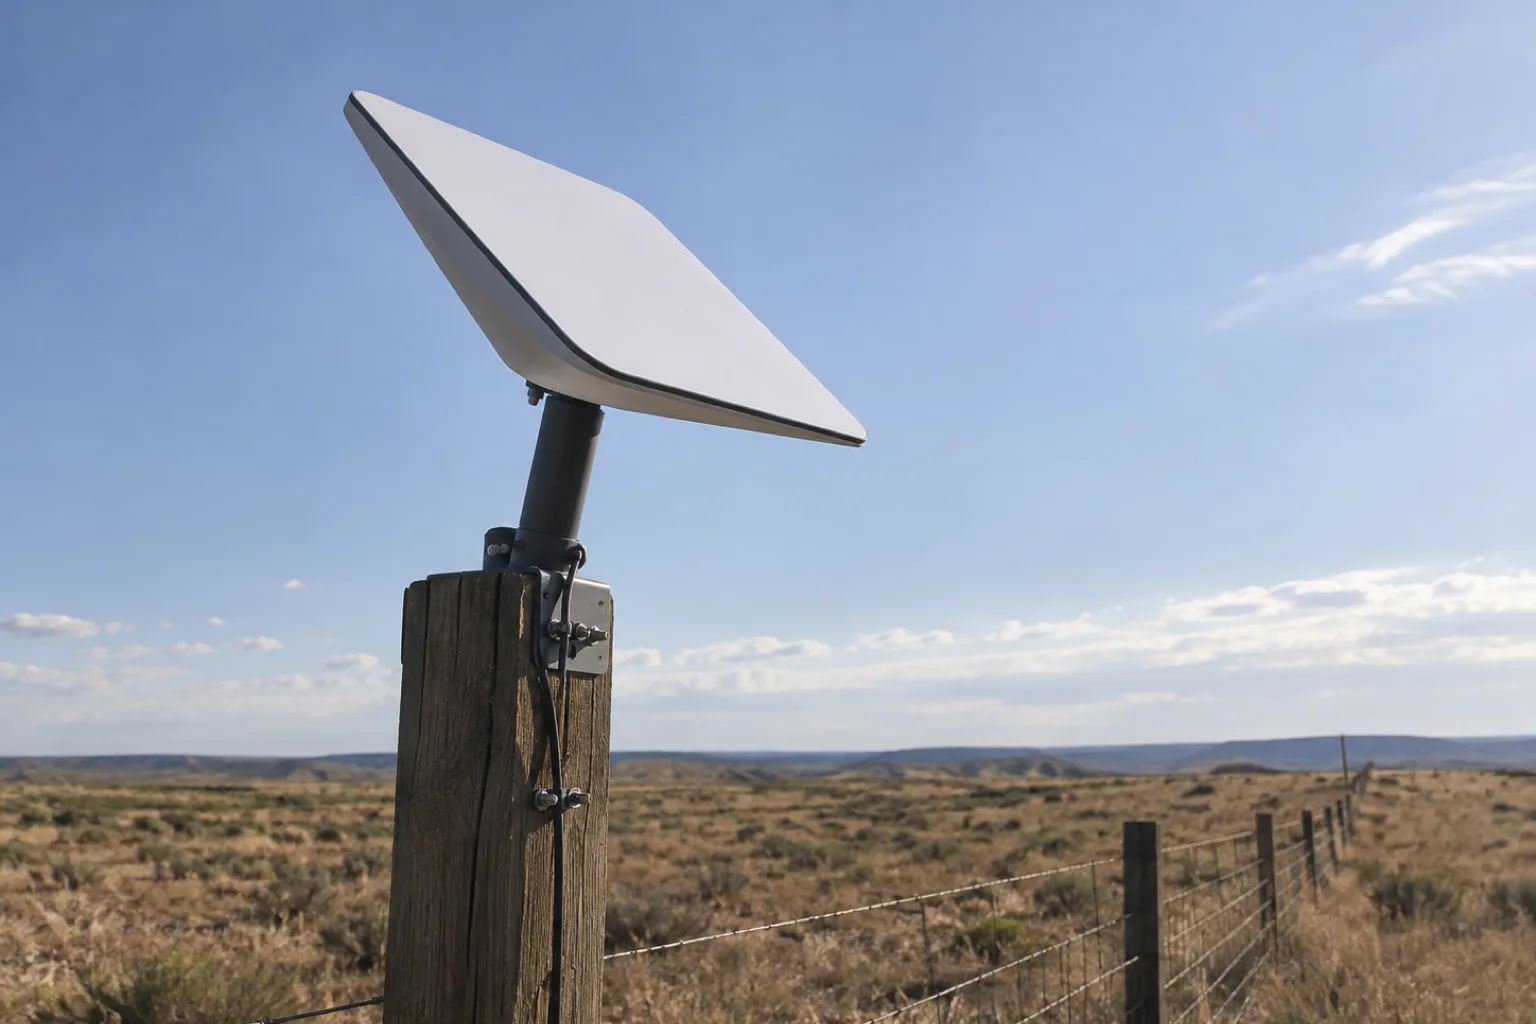
Thirty percent. For several years that figure has been reported as the reason satellite internet has not properly arrived in South Africa. South Africa requires that a share of an electronic communications license holder be owned by historically disadvantaged South Africans, and that requirement has been the visible obstacle in a long and public standoff with Starlink.
Two weeks ago Amazon began selling satellite internet in South Africa without the rule being changed, waived or litigated. It is worth understanding exactly how, because the mechanism is not a loophole in the sense of something hidden. It is a plain reading of what the rule attaches to, and the rule attaches to the license holder.
What the rule actually governs
Start with the structure, because the reporting has generally collapsed two different things into one.
An electronic communications license in South Africa is a permission to operate a network and sell services over it. It is issued by the regulator to a named entity, and the ownership condition is a condition on that entity. It asks who owns the license holder.
It does not ask who manufactured the equipment. It does not ask who owns the satellites, who operates the ground stations abroad, who wrote the software, or whose brand is on the terminal in the customer’s window. Those are supply relationships, and a licensed operator buying capacity or hardware from a foreign vendor is the ordinary condition of every telecommunications market on earth.
So the question the rule asks has a narrow subject. Everything turns on which entity is standing in front of the regulator.
The arrangement
On 15 July, Herotel became the first authorized Amazon Leo distributor in South Africa. Herotel is not a small company set up for the purpose. It is the largest fixed internet provider in the country, with an existing network, an existing customer base and an existing license.
The service it will sell is called evry, and it is scheduled to reach residential customers in 2027. The terminals come in two versions, a Nano rated to about 100 megabits per second and a Pro rated to about 300.
In that structure Herotel is the operator. It holds the license, it sells the service, it bills the customer, it carries the regulatory obligations and it answers for them. Amazon is a supplier of space capacity and hardware to a licensed South African operator.
The ownership condition applies, in full, to Herotel. It does not reach through the supply relationship to Amazon, because there is no provision that says it should, and reading one in would mean that every licensed operator in the country became responsible for the ownership structure of every vendor it buys from.
Why the other company could not do this
The obvious question is why Starlink has spent years arguing about the rule instead of doing the same thing, and the answer is a choice about business model rather than a legal difference.
Starlink’s model is direct. The customer buys the terminal from the company, subscribes to the company, and is a customer of the company. That requires the company to be the licensed operator in each market, which puts it directly in front of the ownership condition in South Africa, which is where the standoff has been.
Amazon has chosen a wholesale posture here instead: sell capacity to an established local operator and let that operator own the customer. The tradeoff is real. The wholesale route surrenders the customer relationship, the pricing decision, the support experience and a share of the margin, and it makes the business dependent on a partner’s execution.
What it buys is entry. And it buys entry without asking a government to change a policy that the government has been publicly unwilling to change, which is a considerably cheaper thing to obtain than a regulatory concession.
The general principle
For anyone who deals with regulated markets, this is the part worth carrying away, and it is not specific to satellites.
A rule is written against a legal object. Ownership conditions attach to license holders. Data residency rules attach to controllers. Safety obligations attach to manufacturers or importers, depending on the drafting. Content duties attach to publishers or to intermediaries, and the entire fight in that area is about which.
The practical consequence is that a firm facing a rule has two moves available, not one. It can try to change the rule, which is slow, public, adversarial and usually unsuccessful. Or it can restructure so that it is no longer the object the rule attaches to, which requires giving something up but does not require anyone’s permission.
The second move is not cheating, and it is worth being clear about that, because the framing of clever avoidance gets applied to it reflexively. A rule that says the licensed operator must be locally owned has been complied with here, completely: the licensed operator is a South African company. If the policy intention was broader than that, the drafting would have to be broader than that, and it is not.
One further consequence is worth flagging for the regulator rather than the companies. If the wholesale route becomes the standard way foreign operators enter, the ownership condition will increasingly govern distributors rather than infrastructure owners, which is a different policy from the one the rule was written to express.
Whether it delivers anything
The stated purpose is rural coverage, which is a real gap. Fixed line and mobile networks in South Africa thin out substantially outside the urban corridors, and farming districts have been on expensive, slow or improvised connections for a long time.
Satellite is genuinely suited to that, and going through an operator that already sells to those districts is a better distribution answer than a foreign company mailing terminals into them. Herotel knows where the customers are and already has people who can install and service equipment in a farming area, which a satellite operator entering cold does not.
The caution is pricing, and it will decide whether any of this matters. Wholesale arrangements add a margin layer, because two companies now need to earn from one subscription. That pressure lands on the retail price, and the retail price is the entire question in markets where the problem has never been that connectivity was unavailable but that it was unaffordable.
Nothing announced on 15 July answers that. The terminals have speeds attached and no prices, and the service does not reach customers until next year. When the first evry tariff sheet is published, the monthly figure on it will have to be set against what a farming household in Limpopo pays today for a connection that mostly does not work. Until that comparison can be made, this is an arrangement rather than an outcome.